
Why Singapore Term Life Insurance Has Become Increasingly Popular?
Frequently Asked Questions About Singapore Term Life Insurance
What Many Overseas Clients Want to Know
Over the past six months, I’ve received a growing number of inquiries from overseas clients regarding Singapore term life insurance.
The most common questions usually revolve around these four topics:
- Is Singapore term life insurance really that affordable?
- Is a medical examination required?
- Can the policy be signed remotely without traveling to Singapore?
- How can premiums be paid without a Singapore bank account?
In this article, I’ll answer these questions one by one to help you better understand how Singapore life insurance works for international clients.
1. Singapore Term Life Insurance Offers Exceptional Value
One of the first things that surprises many clients is how affordable Singapore term life insurance can be.
Under similar conditions, premiums in Singapore are often significantly lower than those in mainland China or Hong Kong — sometimes by as much as 1–2 times — while still allowing access to much higher coverage amounts.
For example:
A 35-year-old non-smoking male applying for:
- SGD 1 million of life coverage for 30 years
would pay approximately SGD 630 per year.
If the coverage increases to:
- SGD 2 million for the same 30-year term,
the annual premium is only around SGD 1,135.
For many clients, this level of affordability and coverage is difficult to achieve elsewhere in Asia.
Beyond pricing, another important reason why Singapore insurance is highly regarded internationally is the country’s strong financial reputation, strict regulatory framework, and transparent underwriting standards. For many families, choosing Singapore insurance is also choosing long-term security and peace of mind.
2. No Health Issues Usually Means No Medical Examination
Many clients are concerned about whether a medical examination is required.
In most cases, if there are no significant health issues disclosed in the health questionnaire, no medical examination is needed.
For overseas applicants, the underwriting standards are generally the same as those applied to local Singapore residents.
If there is a history of medical conditions or previous hospitalization, the insurer may request additional medical reports or arrange a medical examination at an approved clinic in the applicant’s home country.
In addition to basic life coverage, clients may also choose to add riders such as:
- Total & Permanent Disability (TPD)
- Critical Illness (CI) coverage
For example:
A 35-year-old non-smoking male with:
- SGD 1 million life coverage
- SGD 1 million TPD coverage
- SGD 300,000 critical illness coverage
- 30-year term
would pay approximately SGD 1,370 annually.
That means roughly RMB 7,000+ per year can provide:
- over RMB 5 million in life coverage
- and more than RMB 1.6 million in critical illness protection.
3. Policies Can Be Signed Remotely Without Traveling to Singapore
Remote application is one of the most frequently asked questions.
Although traveling between China and Singapore has become increasingly convenient, many clients simply do not have the time to fly over.
The good news is that many Singapore insurance products now support remote signing and onboarding processes, making applications far more convenient for overseas clients.
The procedures are generally very similar to local Singapore applications and usually do not involve complicated additional requirements.
Besides term life and term critical illness insurance, certain products such as:
- annuities
- and Indexed Universal Life (IUL) insurance
may also support remote applications, while still providing the same level of policy servicing as local Singapore policies.
Among them, IUL (Indexed Universal Life) has become one of the most discussed wealth-planning solutions in recent years.
Compared with traditional whole life insurance, IUL generally offers:
- lower insurance costs
- flexible premium structures
- downside protection with upside potential linked to market indices
- stronger long-term cash value accumulation opportunities
It can serve both as a legacy planning tool and a long-term financial planning solution.
4. Premiums Can Still Be Paid Without a Singapore Bank Account
Payment methods are another common concern for overseas clients.
Ideally, having a Singapore or Hong Kong bank account makes premium payments more convenient. Fortunately, opening a Singapore bank account online has become much easier in recent years, and in many cases there is no minimum deposit requirement.
In addition, some insurers also support premium payments through designated international credit cards, making the payment process even more accessible for overseas policyholders.
Final Thoughts
The increasing accessibility of cross-border financial services has greatly reduced information barriers.
Today, quality insurance solutions and professional financial protection are no longer limited by geography. More families now have access to international insurance planning options that better fit their long-term protection and wealth goals.
If you would like to learn more about Singapore term life insurance or explore suitable protection solutions, feel free to reach out anytime.
Important: The information and opinions in this article are for general information purposes only. They should not be relied on as professional financial advice. Readers should seek unbiased financial advice that is customised to their specific financial objectives, situations & needs. This advertisement or publication has not been reviewed by the Monetary Authority of Singapore.
Published By:
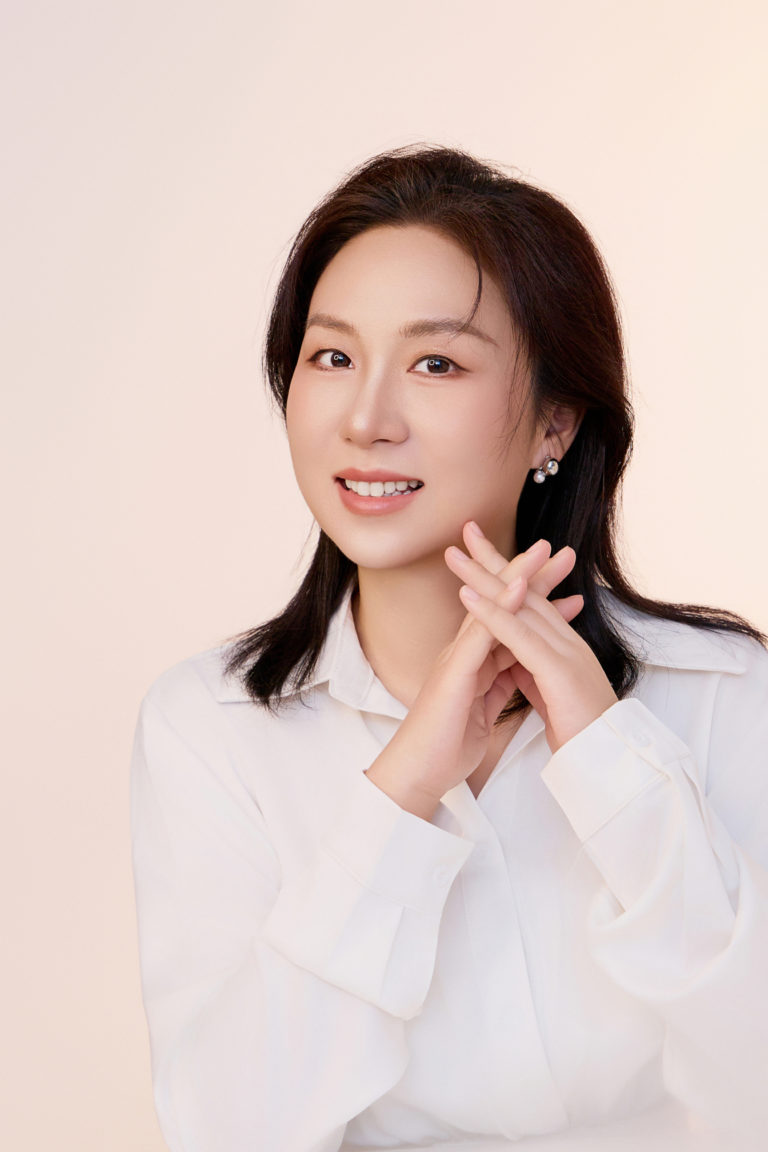
Wynne Wei Ning
您好,我是 Wynne Wei(魏宁)。2008年,我通过全额奖学金来到新加坡,在这里开启了自己的职业生涯。进入金融行业之前,我曾在新加坡公立医院手术室工作近14年。长期在高压、高要求的医疗环境中工作,培养了我严谨的思维、风险意识和决策能力。多年的医疗经历也让我深刻体会到,疾病和意外不仅影响一个人的健康,更可能改变整个家庭的生活。因此,我选择从医疗行业转型进入金融理财行业,希望将过去对生命与风险的理解,转化为对家庭保障和财富规划的专业支持,把风险管理从事后应对变成提前规划。
目前,我是 Financial Alliance Pte Ltd 的金融顾问,专注于保险保障、退休规划、投资配置及财富管理。依托公司覆盖150多家金融机构的资源,我能够比较不同保险公司及投资平台的方案,为客户提供更适合其需求和长期目标的财务规划。我主要服务在新加坡发展的专业人士、企业主、新移民家庭及高净值人士,不仅关注财富增长,更重视风险管理、资产保全、退休现金流及财富传承。
与此同时,我也通过小红书、视频号、Instagram及YouTube 分享新加坡保险、CPF、SRS、退休规划及财富管理知识,希望帮助更多家庭减少信息差,在重要的财务决策上少走弯路。我始终相信,财富管理不仅是数字的管理,更是对一个家庭未来的责任。如果您希望为自己和家人建立更清晰、更稳健的财务规划,我很乐意从一次真诚的交流开始。
欢迎联系我,点击“预约咨询”。
WA:+6581267108
WeChat:wynne_weining
CONTACT US
- 150 Beach Road #12-01/08, Gateway West Singapore 189720
- +65 62221889
- +65 62221019
- feedback@fa.com.sg