Your Insurance May Not Be Your Financial Plan
The insurance policies you bought might eventually become less useful than you think.
Not because insurance is bad.
But because the purpose of insurance changes as you get older.
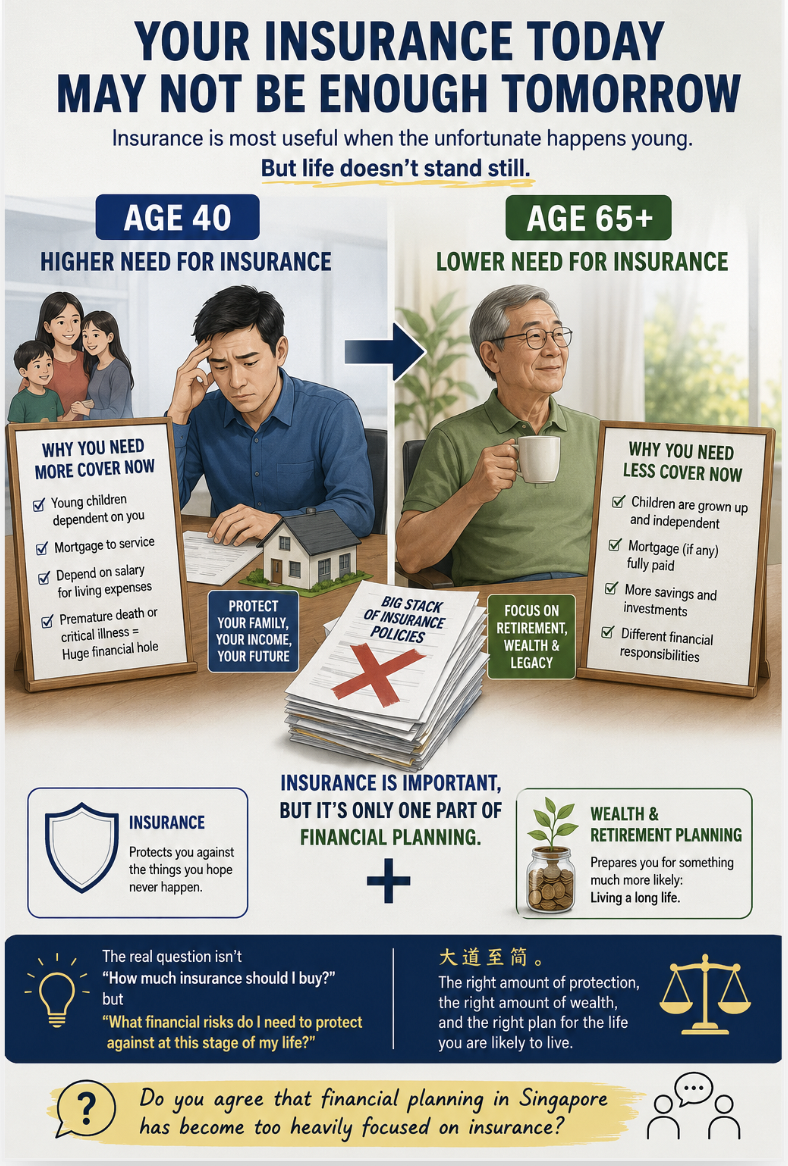
Insurance is most valuable when something unfortunate happens too early.
When your children are still young and dependent on you.
When you are still servicing a mortgage.
When your family depends on your salary to maintain their lifestyle.
When a premature death or critical illness could create a huge financial hole.
At age 40, you may need a significant amount of insurance.
But what about age 65?
By then, your children may have grown up and become financially independent.
Your mortgage may be fully paid.
You may have accumulated substantial savings and investments.
Your financial responsibilities may be very different.
And if something happens to you at 70, you probably don’t need the same amount of insurance you needed at 40.
This is why I sometimes feel uncomfortable when I see a client’s financial plan consisting mainly of a thick stack of insurance policies.
Don’t get me wrong.
Insurance is important.
But insurance is only one part of financial planning.
In Singapore, I think we have become too accustomed to thinking:
Financial planning = Insurance planning.
I believe that’s a mistake.
Because the reality is, most of us will not die young.
Most of us will live into our 70s, 80s and beyond.
And if we are fortunate enough to live that long, the bigger financial challenges may not be:
“How much insurance do I have?”
They may be:
“Will my money last?”
“Am I accumulating enough wealth?”
“How much can I spend in retirement?”
“How do I protect my wealth?”
“How do I pass it on efficiently to my children?”
Insurance protects you against the things you hope never happen.
But wealth accumulation and retirement planning prepare you for something much more likely:
Living a long life.
Perhaps the real question isn’t:
“How much insurance should I buy?”
But:
“What financial risks do I need to protect against at this stage of my life?”
That’s a very different question.
大道至简.
Good financial planning isn’t about having the most insurance.
It’s about having the right amount of protection, the right amount of wealth, and the right plan for the life you are likely to live.
Do you agree that financial planning in Singapore has become too heavily focused on insurance?
#FinancialPlanning #RetirementPlanning #InsurancePlanning #WealthManagement #Singapore #EstatePlanning #FinancialFreedom
Important: The information and opinions in this article are for general information purposes only. They should not be relied on as professional financial advice. Readers should seek unbiased financial advice that is customised to their specific financial objectives, situations & needs. This advertisement or publication has not been reviewed by the Monetary Authority of Singapore.
Published By:
Tan Siak Lim
More than 20 years in the financial advisory business, focus on mainly help people achieve a comfortable retirement through portfolio management, with diversification to reduce the votaility and still achieving the required rate of return.
Also helps wealthy family (>$3m estate, including property, investment and insurance proceeds) pass on their wealth to future generations, minimizing the 3C, confusion, cost, and conflict. Estate planning is probably best done by a qualified experienced financial adviser rather than a lawyer. The lawyer is able to draft a will, but because he is not a financial adviser, he is usually unable to put comprehensive financial consideration into the design of the will. Will drafting is a mechanical process that software can easily generate, there is little value. It is the architecting of a wealth distribution strategy with creative financial products and ideas that is the real value.
CONTACT US
- 150 Beach Road #12-01/08, Gateway West Singapore 189720
- +65 62221889
- +65 62221019
- feedback@fa.com.sg